Virtual CFO in India: From the Munim to the Dashboard, How the Role Changed and What a Business Should Expect in 2026
Discover how virtual CFO services evolved in India, how technology is changing financial management, and when businesses need support with cash flow, MIS reporting, lenders and strategic decisions.
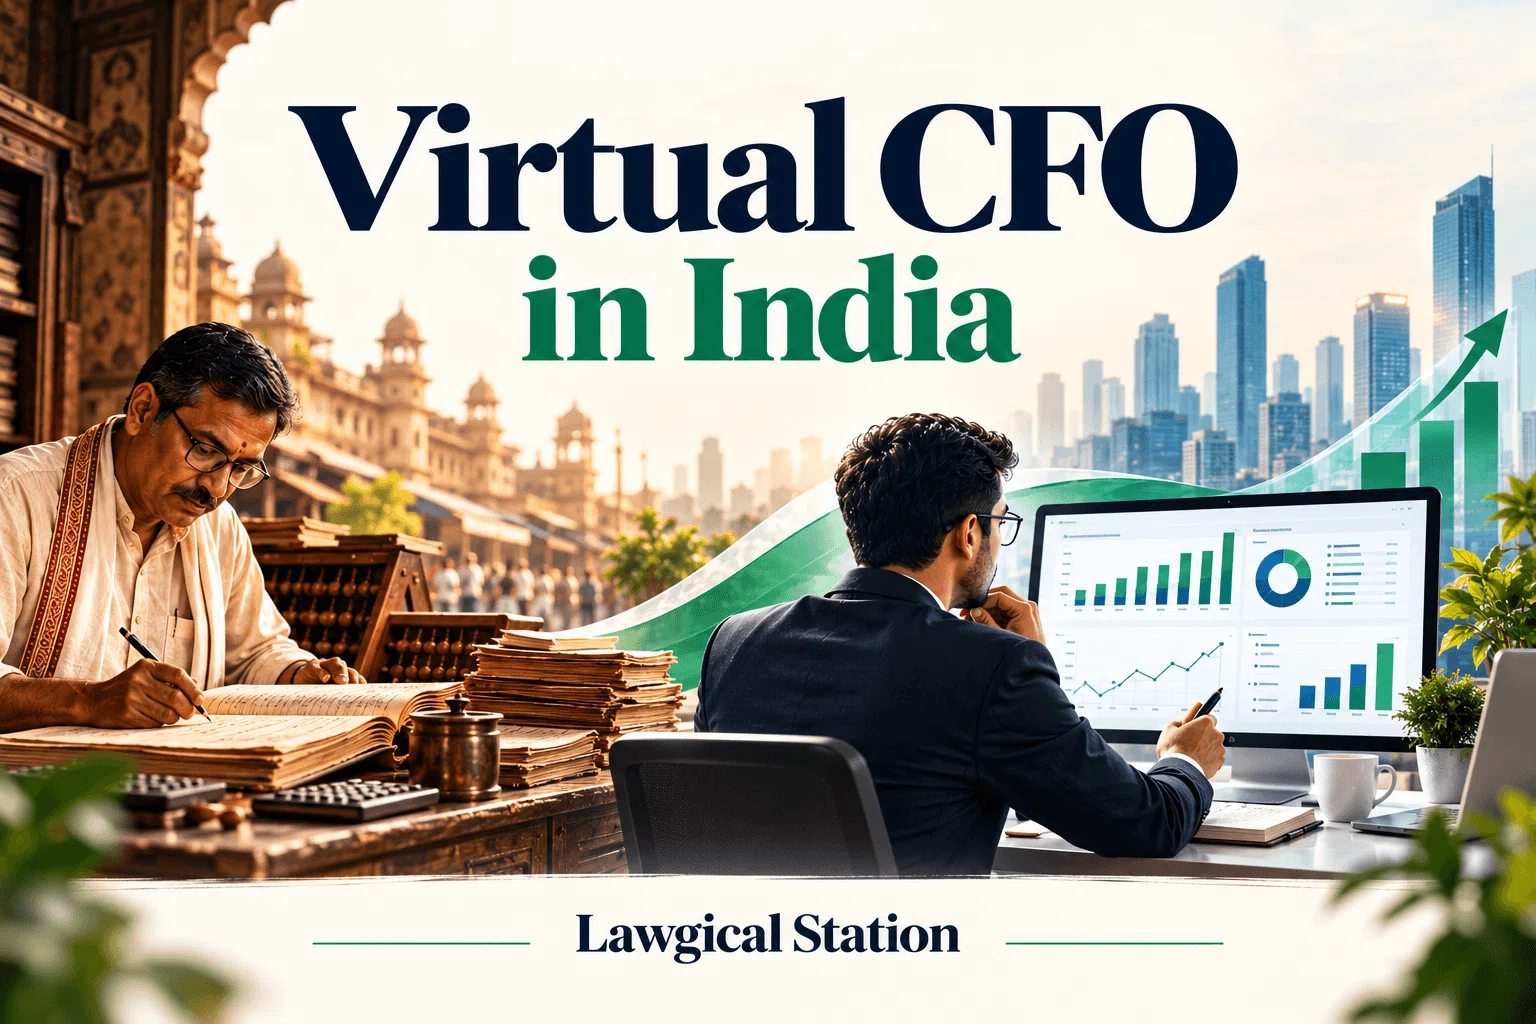
For a long time, the person who "managed the money" in an Indian business was the munim. Sometimes it was a father's trusted accountant, sometimes a clerk who had been in the shop for twenty years. He kept the books, knew every party by name, and could tell you from memory who owed what.
That system worked for a long while, and it deserves some respect. But businesses got bigger, banks started asking for different things, and one question became harder to answer from a ledger: "If we are making profit, why is there no cash?"
This article explains how that question gave rise to the virtual CFO, what the old way looked like, what has changed in the last few years, and what a business should expect today.
The short version
- The old pattern: a munim or accountant records the past, and a CA handles compliance. A full-time CFO appears only in large companies.
- The virtual CFO idea reached India around 2009 to 2010, driven by startups and SMEs (Wikipedia; Finance Story interview).
- What is new: data now moves between GST, banks and lenders with consent, receivables can be financed through regulated platforms, and routine accounting is increasingly automated.
- That shifts the value from recording numbers to interpreting them.
- A virtual CFO is not a bigger accountant. It is a different job.
The old pattern, and why it held for so long
Layer 1: the bookkeeper (the munim). Daily entries, party balances, stock, cash in hand. Strength: deep knowledge of people and the day-to-day. Gap: no forward view, no strategy.
Layer 2: the CA or CS firm. Returns, audit, GST, ROC filings, certificates. Strength: compliance and credibility. Gap: this work is largely periodic and backward-looking, which is why most businesses hear about problems after the quarter closes.
Layer 3: the full-time CFO. Planning, cash, lenders, investors, board. Strength: everything the first two lack. Gap: out of reach for most small and mid-sized businesses, who cannot justify the cost and cannot easily find the right person.
Sanjay Gaggar, who founded one of India's early outsourced-CFO firms, put it simply in a 2023 interview: the old model was the traditional "muneem", with no strategic finance leadership. The newer model is a CFO or controller engaged part-time or by project, for strategic and process work, hands-on rather than purely advisory (The Finance Story, 8 November 2023).
How the virtual CFO idea reached India
In that interview, Gaggar describes qualifying as a CA in 1993, working in corporate finance roles, becoming CFO of a venture-backed edtech startup in 2006, and starting an outsourced CFO firm in 2010. His first year brought no mandates. From the second year, clients began to come, mostly businesses between about ₹50 crore and ₹500 crore in revenue.
Why did it start working? He lists several drivers:
- More startups and more venture and private equity money.
- Startups that struggled to manage their finances.
- Family businesses where a new generation wanted professional finance leadership.
- Investor-backed companies that needed CFO support before hiring a full-time CFO.
He also notes that CFO services firms emerged in the US around 2000 and took roughly ten years to gain traction. The Wikipedia entry on the topic dates adoption in India to around 2009 to 2010, driven by startups and SMEs.
Two lessons stand out. First, trust takes time, and a first year with no clients is normal. Second, the model grew because a real gap existed: businesses needed CFO-grade thinking without a CFO-grade payroll.
What has actually changed: the new era
It is easy to say "technology changed everything". Here are four specific shifts, each with a source.
1. Financial data now moves with consent
The Account Aggregator framework, regulated by the RBI, lets a person or business share financial data between institutions through a licensed consent manager, instead of emailed statements and shared passwords. Commercial operation began in September 2021. Data sources include banks, NBFCs, mutual funds, insurers and the GST network. For lenders, that means a business's GST data, current-account data and bureau data can be combined under one consent. One guide puts the shift as a roughly two-week, paper-based process becoming a same-day digital one. By 31 December 2025, about 2.61 billion financial accounts were enabled for data sharing (HyperVerge, which does not clearly cite its source for every figure).
What it means for a business: Lenders increasingly look at your real cash flow. If your books and your GST data disagree, they notice.
2. Receivables can be turned into cash through regulated platforms
TReDS (Trade Receivables Discounting System) lets an MSME turn an approved invoice into cash before the due date, collateral-free and without recourse to the seller, with banks and NBFCs bidding. Invoice discounting rose from ₹40,000 crore in FY 2021-22 to ₹3.47 lakh crore in FY 2025-26. Five platforms operate: RXIL, M1xchange, Invoicemart, C2treds and DTX. On 30 June 2026, the MSME Ministry notified that central public sector enterprises must settle MSME supplier invoices through TReDS (PIB, 10 July 2026).
What it means: How and when you invoice, and to whom, now changes your financing options.
3. Rules on money have become more specific
In Uttar Pradesh, the revised RERA banking rules issued on 11 May 2026 require builders to keep 70% of homebuyer money in a specified account, with withdrawals needing sign-off from the project engineer, architect and chartered accountant, and no use of the money for another project (Outlook Money). The GST Council's 57th meeting on 8 October 2026 also recommended faster refunds and wider input credit, though those are recommendations and not yet law (TaxGuru).
What it means: Finance decisions are tied more closely to compliance, and a mistake shows up quickly.
4. Routine accounting is being automated
An ICAI Southern Regional Council e-book from 2022 cites a 2018 ACCA and Deloitte study finding a high probability, over 50%, of automation for many finance and accounting functions, and argues that higher-level planning and strategy roles are less likely to be automated. The authors note that their views are their own and not ICAI's.
What it means: The value of finance support moves from typing numbers to understanding them.
Old pattern versus the new era
| Area | The old pattern | The new era |
|---|---|---|
| Who | Munim or accountant, plus a CA for filings | Part-time senior finance lead working with your CA |
| Reports | Monthly or quarterly, often late | Regular management reports, often built from connected data |
| Data | Typed in from bills and vouchers | Pulled from accounting software, banks and GST |
| Focus | What happened | What is likely to happen and what to do |
| Cash | "How much is in the bank?" | A rolling forecast of cash for the coming weeks |
| Lenders and investors | A file of papers when asked | A prepared pack, ready in advance |
| Value | Accuracy and compliance | Judgment and decisions |
A worked example: the cash gap (an illustration)
These figures are assumptions for illustration, not a client case.
Take a manufacturer with ₹12 crore of yearly sales and ₹9 crore of cost of goods. Assume it holds stock for 45 days and pays suppliers in 30 days. Now use the average invoice payment time of 73 days reported for Indian SMEs in the Recordent 2026 report (against the government's 45-day guideline).
Money tied up in the business:
- Customers owe: ₹12 crore × 73 ÷ 365 = ₹2.40 crore
- Stock: ₹9 crore × 45 ÷ 365 = about ₹1.11 crore
- Less what it owes suppliers: ₹9 crore × 30 ÷ 365 = about ₹0.74 crore
- Net cash locked in operations: about ₹2.77 crore
Now suppose collections improve from 73 days to 45 days:
- Customers owe: ₹12 crore × 45 ÷ 365 = about ₹1.48 crore
- Net locked cash falls to about ₹1.85 crore
- Cash released: about ₹92 lakh
Nothing about profit changed. The business simply got paid sooner. A good virtual CFO watches these day-counts every week, asks which customers are stretching, and checks whether financing an invoice makes sense for a large buyer. That is the unglamorous heart of the job.
What a virtual CFO does in 2026
Finnova Advisory lists eight areas: budgeting and forecasting, MIS and board reporting, cash and working capital, lender and debt management, tax, MCA and ROC compliance, accounting and controls, and fundraising. Typical engagements run 20 to 40 hours a month. New engagements usually start with clean MIS, a cash forecast and a lender-ready file, then widen in scope.
Here is a plain monthly rhythm:
- Books closed and reconciled.
- A short report: profit by product or branch, cash position, who owes you, whom you owe.
- A budget-versus-actual review and the reasons for gaps.
- A look at the next 13 weeks of cash.
- A conversation about decisions: hire, buy, borrow, or wait.
The honest limits
- It does not replace your CA. Finnova notes that a virtual CFO usually works alongside one.
- The ICAI e-book is blunt that an existing CA team usually needs new skills to deliver this, such as financial modelling, business understanding and digital capability. That is a reason to ask any firm what experience it really has.
- It is not for every business. A very early business with a handful of transactions may do fine with a good accountant and a quarterly review.
- It needs the owner's time. Without a monthly conversation, the reports go unread.
- There is no official qualification for the role (Wikipedia). The title can be used loosely, so look at the work, not the label. KayOne Consulting argues that very low-priced offers are usually bookkeeping labelled as CFO work.
What it costs, in plain words
- It is usually far less than a full-time CFO. One provider puts it at roughly a quarter to a third of the cost for comparable seniority (Finnova, who sells the service).
- It costs more than bookkeeping, and it should.
- Gaggar describes pricing as value-based and tied to defined deliverables.
- The fee depends on your size, the number of entities, banking and lender relationships, how often you want reviews, and whether a fundraise is coming.
- Only 2 of more than 20 Indian providers published a real rate card in one 2026 cost study (KayOne), so you will usually need a conversation to get a price.
Questions to ask before you hire
- Who exactly will work on my account, and how many hours a month?
- What will I receive each month, and by which date?
- How will you work with my CA?
- Have you handled a business like mine?
- Who on your team has run a finance function inside a business?
- What happens in the first 90 days?
- What is not included?
- How do I exit if it does not work?
How we approach it at Lawgical Station
We came to this from the compliance side: tax, GST, company law and audit. That gives us a useful starting point, because clean books, matching GST data and tidy filings are the foundation of everything above. It also means we take seriously what the ICAI book says about building new skills deliberately. When a business talks to us, we look at the cash cycle, the reports and the plans first, and tell them honestly which stage they are at: tighter reporting, a part-time CFO, or just a better monthly review. We work with businesses across India, whether you are in Meerut, Agra, Delhi NCR or Mumbai.
FAQs
1. What is a virtual CFO?
An outsourced senior finance professional who provides CFO-level support to several clients, part-time (ICAI SIRC e-book; Finnova).
2. Is a virtual CFO the same as a fractional or outsourced CFO?
In practice the words are used interchangeably. What matters is the scope and accountability.
3. How is a virtual CFO different from a CA?
A CA firm focuses on compliance and assurance. A virtual CFO focuses on planning, cash and decisions, and usually works with your CA.
4. When did virtual CFO services start in India?
Around 2009 to 2010, driven by startups and SMEs (Wikipedia; The Finance Story).
5. Is there a qualification for a virtual CFO?
There is no official requirement, so judge by experience and work (Wikipedia).
6. What does a virtual CFO do every month?
Closes and reviews the books, produces management reports, reviews cash, receivables and payables, and advises on decisions.
7. Is a virtual CFO worth it for a small business?
It can be when cash is tight, reports are late, or a loan or fundraise is coming. For very simple businesses, better accounting may be enough.
8. What is MIS?
A regular report that shows profit, cash, receivables, payables and budget gaps.
9. How is the fee decided?
By scope, size, complexity and how often you want reviews.
10. Can a virtual CFO help with bank loans?
Yes. Lender management is part of the usual scope.
11. What is TReDS?
A regulated platform that lets MSMEs convert approved invoices into cash before the due date (PIB).
12. Do you serve my city?
We work with businesses across India.
If you want to see where your business stands
Most owners know their sales and their bank balance. Far fewer know their collection days, their cash forecast or what a lender would see in their data. If you want a second pair of eyes on that, our team is happy to look at it with you.
General information only, not financial advice. Figures and sources last verified on 19 October 2026.
The Lawgical Station team brings together CAs, CSs and tax specialists with decades of combined experience advising founders, SMEs and professionals on tax, compliance and business structuring across India.