Why Your UPI Settlement Is Short After October 15 — And How Much You Can Legally Claim Back
UPI MDR of 0.4% starts October 15, 2026 on payments above ₹2,000. But the real cost is higher: 18% GST applies to the MDR itself. Here's who can claim that GST back, who can't, and how much your UPI settlement actually loses.
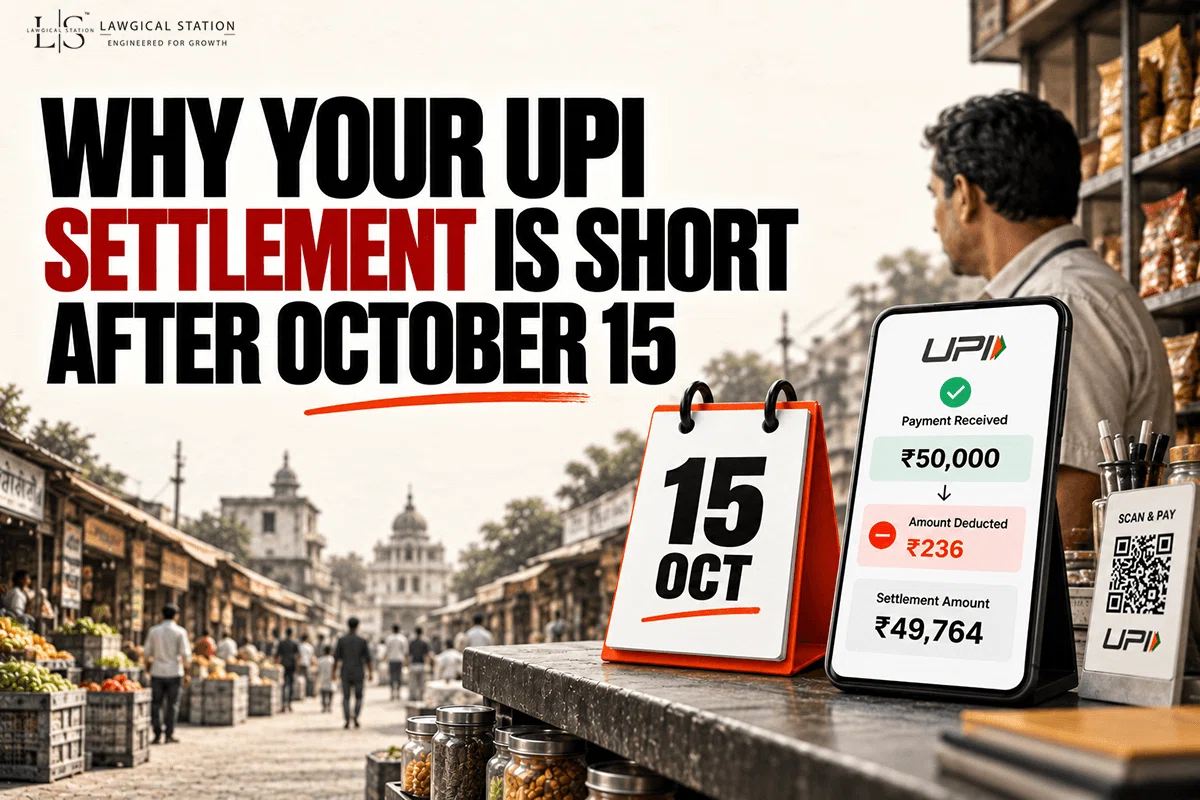
If you run a business that accepts UPI payments, October 16 is the day your bank settlement stops matching what the customer actually paid. A ₹50,000 sale lands as ₹49,764. Nobody tells you why on the statement. Here's the full picture, and more importantly, how much of that gap you can actually get back.
What changed, in one line
From October 15, 2026, NPCI's Merchant Discount Rate framework applies a 0.4% fee on person-to-merchant UPI payments above ₹2,000, capped at ₹300 once a transaction crosses ₹75,000. Person-to-person transfers stay free forever. Small merchants doing under ₹1 lakh a month in UPI volume stay exempt regardless of transaction size. Railways, telecom, insurance, fuel, and agri inputs above ₹2,000 get a flat ₹5 instead of the percentage. Mutual funds and brokers pay 0.02%, capped at ₹300.
Source: NPCI gazette notification, September 14, 2026; Business Standard, September 16, 2026.
That part, most people covering this topic have explained. What almost nobody has covered is what happens next, and it's the part that actually affects your bottom line.
The charge nobody mentioned: 18% GST on the fee itself
A CBIC official confirmed the MDR itself attracts 18% GST, treated as a payment settlement service. This tax applies only to the MDR amount, never to your sale value.
| Transaction | MDR (0.4%) | GST on MDR (18%) | Total deducted from your settlement |
|---|---|---|---|
| ₹5,000 | ₹20 | ₹3.60 | ₹23.60 |
| ₹10,000 | ₹40 | ₹7.20 | ₹47.20 |
| ₹50,000 | ₹200 | ₹36 | ₹236 |
| ₹75,000 and above (capped) | ₹300 | ₹54 | ₹354 |
Source: CBIC official cited in Free Press Journal, September 17, 2026; corroborated by AMRG Global and Nangia Global tax experts, Business Standard, September 16-17, 2026. This is expected to generate ₹3,500-4,000 crore in annual GST collections nationally.
Here's the part that changes your actual cost: you may be able to claim that 18% back
If you're GST-registered, you can claim Input Tax Credit on the GST charged on the MDR, exactly the way most businesses already do for card-payment MDR today. But whether you get full credit, partial credit, or none at all depends entirely on your business type, and this is where most people get it wrong.
| Your business type | Can you claim ITC on the GST paid on MDR? |
|---|---|
| Regular GST-registered, 100% taxable supplies | Yes, in full, subject to standard ITC conditions |
| Composition scheme | No, ITC isn't available under composition at all |
| Mixed taxable and exempt supplies | Restricted, only proportionate to your taxable turnover |
| Unregistered | No, you bear the full 18% as a real cost |
Source: Ikesh Nagpal, Lead-Indirect Tax, AKM Global, Business Standard, September 16, 2026.
Three real businesses, three completely different outcomes
The rule reads identically for everyone. What you actually recover doesn't. Here's how it plays out for three different kinds of businesses.
Ramesh runs a garment store, regular GST scheme, 100% taxable goods. A customer pays him ₹8,000 by UPI. MDR is ₹32, GST on that is ₹5.76, so ₹37.76 gets deducted from his settlement. Because his entire turnover is taxable, Ramesh claims the full ₹5.76 back as ITC in that month's return. His real, final cost is just the ₹32 MDR, and even that he can deduct as a business expense against his income tax. The GST portion, in effect, costs him nothing once he files correctly.
Dr. Anita runs a diagnostic clinic. Basic diagnostic services are GST-exempt, but she also sells supplements and imaging prints at the counter, which are taxable. A patient pays ₹6,000 by UPI, ₹4,500 of it for exempt diagnostic services and ₹1,500 for taxable supplements. MDR comes to ₹24, GST on that is ₹4.32. Because most of that receipt relates to an exempt supply, Dr. Anita can only claim ITC proportionate to the taxable portion, not the full ₹4.32. Across her overall receipts, she recovers only a fraction of what she's paying in GST on MDR, and the rest becomes a real, unrecoverable cost. Clinics, coaching centres, and any business with a mixed exempt-and-taxable revenue stream fall into this category, and it's exactly where people assume full recovery and lose money quietly, month after month.
Suresh runs a kirana under the GST composition scheme. A customer pays ₹3,000 by UPI. MDR is ₹12, GST is ₹2.16, ₹14.16 total deducted. Composition taxpayers cannot claim ITC under GST law, period. Suresh bears the full ₹14.16 with zero recovery. His only relief is that the ₹12 MDR portion, not the GST, can still be claimed as a business expense deduction under income tax, since that's a separate rule from GST-ITC eligibility. Worth noting: most kirana stores this size fall under the ₹1 lakh/month small-merchant exemption and pay zero MDR in the first place. This example only bites once volume crosses that line.
Can you deduct the MDR itself from your taxable income?
Yes. Under the general principle in Section 37(1) of the Income Tax Act, 1961, any expenditure incurred wholly and exclusively for business purposes is deductible while computing taxable business income. Bank charges, payment gateway fees, and transaction processing costs have always fallen into this bucket. MDR is functionally identical to what banks already charge on card transactions, a routine, long-accepted deduction. No fresh notification is required for this treatment to apply.
One honest gap: the Income Tax Act, 2025 restructures and renumbers this entire chapter, effective for income earned from April 1, 2026, and UPI MDR starts October 15, 2026, squarely inside that new framework. The exact corresponding section number for this provision under the new Act wasn't consistently confirmed across public sources at the time of writing. The principle isn't in doubt, a genuine payment-processing cost is deductible. The precise citation is something to confirm with your CA before it goes into an actual filing.
Putting the full math together
On a ₹50,000 UPI sale, without any relief you're out ₹236. With ITC claimed correctly and the expense deducted, your real cost drops to roughly the ₹200 MDR alone, the GST recovered, and even that ₹200 lowers your taxable profit. Scale that to a business doing ₹50 lakh a year in eligible UPI collections above ₹2,000, and the difference between claiming this correctly and not claiming it at all is the difference between a real annual cost of ₹20,000-24,000 and one closer to ₹20,000, with the GST fully clawed back.
That gap doesn't close itself. It closes when your returns correctly separate taxable and exempt turnover, and most businesses with a mixed revenue profile, clinics, coaching institutes, part-exempt retailers, don't track this cleanly enough to get it right without it being flagged for them.
Frequently asked questions
Does GST apply to my whole UPI payment, or just the fee?
Only the MDR fee. An 18% GST applies to the 0.4% charge itself, never to your sale value.
Can every business claim the GST back?
No. Regular GST-registered businesses with fully taxable supplies get full ITC. Composition scheme businesses get none. Mixed taxable-and-exempt businesses get a proportionate share. Unregistered merchants get none.
Is the MDR itself tax-deductible?
Yes, as a standard business expense under the same principle that already allows bank and card-processing charges as deductions. Confirm the exact section reference under the new Income Tax Act, 2025 with your CA before filing.
I run a clinic or coaching centre with mixed revenue. What should I actually do?
Get your taxable-versus-exempt split calculated properly before your first post-October 15 GST return is due. Guessing this proportion, or assuming full ITC, is exactly how businesses either underclaim every month or overclaim and get flagged later.
Know exactly where your business falls, full recovery, partial, or none, and what that means for your GST return and your income tax filing this year. Reach out before your first post-October 15 return is due, not after.
Call/WhatsApp: 90453 56687 | lawgicalstation.com
The Lawgical Station team brings together CAs, CSs and tax specialists with decades of combined experience advising founders, SMEs and professionals on tax, compliance and business structuring across India.